Back to ryanvet.com The Ryan Vet Show
Staying Relevant Season 1 · Episode 54 · Guest

Orphe Divounguy: The Affordability Squeeze, the Fed's Misread, and Housing Is the Heartbeat

43:16 September 14, 2026 With Orphe Divounguy

Follow the show in your app. Apple leads on iPhone, Spotify on Android.

Summary

The economy looks fine on paper. Orphe Divounguy builds the models behind that paper, and he is telling you the paper is wrong.

Orphe Divounguy is the founder and chief economist of the Quantitative Research Group and a former Zillow economist, where he built the first simple measure of the national housing deficit. His argument here is more pointed than economists usually make out loud: the official read of the American economy is misleading, and housing is the reason. Of the 1.5% real GDP growth in the second quarter, 1.2 percentage points came from intellectual property and equipment tied to the AI build-out. Strip that out and the rest of the economy is barely moving. Unemployment at 4.1% looks healthy until you go looking for recent graduates who cannot find work. The averages are fine. The distribution is not.

Underneath it is an affordability problem with a number attached. By his math a median-income Los Angeles household would need a down payment of roughly $790,000 to keep housing at 30% of income. The country is short about 4.3 to 4.5 million units, concentrated in exactly the coastal metros where people most want to live. And mobility has collapsed for three reasons at once: the weakest hiring rates since just after the global financial crisis, rate lock on pandemic-era 3% and 4% mortgages, and renters whose current rent beats anything on the market.

His point is that stalled mobility is not a side effect, it is the problem. If engineers cannot move to where a new technology is being built, the technology does not get built. Host Ryan Vet puts a countertop number on the same country: at his flagship coffee shop the average ticket is down almost 40% while the ticket count holds steady. Smaller coffees, no pastry, no add-ons. Orphe's datasets and Ryan's register are describing the same economy.


Key takeaways
1

1.2 of the 1.5 percentage points of Q2 real GDP growth came from intellectual property and equipment tied to the AI build-out. Strip that out and, in Divounguy's words, the rest of the economy is barely growing.

2

A 4.1% unemployment rate is an average, not a description. It does not capture the highly educated recent graduates who cannot find work, which is why he warns that people read the headline and never look at the distribution.

3

For a median-income Los Angeles household to keep monthly housing costs at 30% of income against the typical local home value, the down payment would need to be roughly $790,000. That is the wall, and it is why coastal homeownership rates are so low.

4

The United States is short roughly 4.3 to 4.5 million housing units. Divounguy's measure is deliberately simple: count families living in the country, subtract units available to rent or buy, and stop there. The largest deficits are in New York, Seattle, San Jose, San Francisco, and Los Angeles.

5

American mobility stalled for three reasons at once: hiring rates at their weakest since just after the global financial crisis, rate lock on pandemic-era 3% and 4% mortgages against market rates near 6.7%, and renters staying because market rents now exceed what they already pay.

6

Gen Z is buying, just not where the headlines look. They are renting in New York and buying in Alabama and Tennessee, co-buying with friends, or reaching the first rung through what he calls the bank of mom and dad.

7

The silver tsunami will not rescue the coasts. The largest share of older homeowners who own outright live in the Midwest, which is already relatively affordable, so the supply does not appear where the demand is.

8

Roughly 42% of core inflation is housing, which is why Divounguy calls housing the heartbeat of the US economy: make it affordable and you restore churn in the labor market, and the churn is what drives growth.


Terms defined

Plain-language definitions for the ideas in this episode. Structured for search and AI answers.

housing is the heartbeat noun · Orphe Divounguy framework

Housing treated as the transmission mechanism for the rest of the economy. Make it affordable and you restore churn in the labor market, which restores growth. Roughly 42% of core inflation is housing.

In this episode: His own phrase, and the line he says he coined.

the affordability squeeze noun · economics

The combined hit of rising goods prices, rising borrowing costs, and flat real incomes, landing hardest on the middle and the bottom of the distribution while the top end, cushioned by home equity and stocks, feels fine.

In this episode: Why the top end is doing great and the middle and bottom are struggling at the same moment.

rate lock noun · housing economics

Homeowners who refinanced into 3% and 4% mortgages during the pandemic and will not move while market rates sit near 6.7%, because the same house would cost far more per month.

In this episode: One of the three forces freezing American mobility.

the simple housing deficit noun · housing economics

Count the families living in the United States, subtract the housing units available for rent or sale, and take the gap, with no assumptions layered in about who should be forming a household. The answer is roughly 4.3 to 4.5 million units.

In this episode: The measure he built at Zillow, and the one that travels furthest.

the bank of mom and dad noun · housing

Family money used by younger buyers to reach a first down payment, alongside co-buying with friends.

In this episode: One of the ways Gen Z is actually getting onto the ladder.

the silver tsunami noun · demographics

The expected wave of housing supply released as older homeowners pass on their homes. Divounguy's caveat is that the paid-off homes sit largely in the already affordable Midwest, not in the coastal markets where young people cluster.

In this episode: Why he does not think the coming transfer fixes coastal affordability.


Notable quotes

Lines worth keeping, verbatim from the episode.

Housing is the heartbeat of the U.S. economy.
Orphe Divounguy 00:27
I feel like the Fed chair is misreading the US economy.
Orphe Divounguy 28:18
1.2 percentage points of the 1.5% growth is all intellectual property and equipment.
Orphe Divounguy 00:01
So the top end is doing great, right? But the middle and the bottom is really struggling right now.
Orphe Divounguy 00:27
most people see these headlines and they see the average, right? They don't look at the distribution
Orphe Divounguy 28:18
you needed to come up with a down payment of roughly $790,000
Orphe Divounguy 00:27
They're renting in New York and they're buying in Alabama, they're buying in Tennessee
Orphe Divounguy 09:22
the people who choose to move have always gone from a more expensive to relatively less expensive market
Orphe Divounguy 15:52
people are going to get stuck in places that are not necessarily good for them
Orphe Divounguy 21:21
Welcoming people, right, by making things relatively more affordable is how you grow your tax base
Orphe Divounguy 23:31
I think of my agent as my therapist
Orphe Divounguy 34:50
AI is not all bad, it's not the boogeyman.
Orphe Divounguy 38:27
Our ticket prices dropped almost 40%. Not that people aren't getting their coffee, they're getting smaller coffees, they're not getting the pastry.
Ryan Vet 00:21

Chapters

Jump to any moment. Timestamps deep-link the audio.


The guest
OD Headshot pending

Orphe Divounguy

Founder and chief economist, Quantitative Research Group

Orphe Divounguy has spent nearly two decades helping executives, investors, policymakers, and the public make sense of the economy, translating complex analysis of housing, labor markets, and fiscal policy into clear, forward-looking guidance they can act on. He is the founder and chief economist of the Quantitative Research Group, and a former Zillow economist. His research and economic commentary reaches millions through national media and through his own podcast, Everyday Economics. He holds a PhD in Economics.

He was born and raised in Gabon, a small country on the equator. His parents moved the family to France when he was a child, for the schools, and he went through the French school system. He spent almost 10 years in England earning a PhD in economics, focused on macroeconomics and specifically on the labor and housing markets. He then moved to the United States, worked on economic policy and its effects on those same markets, and joined Zillow, where he studied how the macro picture, interest rates, the labor market, the state of the consumer, feeds through into housing outcomes.

At the Quantitative Research Group he consults for home builders, capital allocators, and multifamily operators on where demand will outrun supply, which regions are heating and cooling, and where Americans are actually moving to and from. The work that travels furthest is a deliberately simple one he built at Zillow: count the families living in the United States, compare that against the housing units available to rent or buy, and take the gap. No assumptions about who ought to be forming a household. The answer comes out around 4.3 to 4.5 million units short, concentrated in the coastal metros where people most want to live.


Frequently asked

Straight answers to the questions this essay raises. Open by default, structured for search and AI.

Why does Orphe Divounguy say the economy is being misread? +

Because the headline numbers describe an average very few people are living in. Real GDP grew 1.5% in Q2, but 1.2 percentage points of that came from intellectual property and equipment tied to the AI build-out, which means the rest of the economy is barely growing. Unemployment at 4.1% does not describe the recent graduates who cannot find work. The top end, cushioned by home equity and stocks, is doing well. The middle and the bottom are squeezed.

How large a down payment would a median Los Angeles household need? +

Roughly $790,000. For a median-income household to keep monthly housing costs at 30% of income against the typical Los Angeles home value, the down payment has to do the work the income cannot. That is why homeownership rates on the coasts are so low and why most people there rent.

How short of housing is the United States? +

By Divounguy's measure, roughly 4.3 to 4.5 million units. He built the calculation at Zillow and kept it deliberately simple: count the families living in the United States, compare that to the housing units available for rent or sale, and take the gap, without layering in assumptions about who should be forming a household. The largest deficits sit in New York, Seattle, San Jose, San Francisco, and Los Angeles.

Why has American mobility slowed, and why does it matter? +

Three forces at once. Hiring rates are the lowest since just after the global financial crisis, so the job moves that usually drive relocation are not happening. Homeowners who refinanced into 3% and 4% mortgages will not give them up with market rates near 6.7%, which he calls rate lock. And renters are staying because market rents now exceed what they already pay. It matters because mobility is how people reach better-paying work, and because if engineers cannot move to where a new technology is being built, the technology does not get built.

Where is Gen Z actually buying homes? +

Away from where the headlines look. As he puts it, they are renting in New York and buying in Alabama, and in Tennessee. Some buy in a cheaper market and rent the unit out while working somewhere expensive. Others pool money with friends and co-buy, or draw on what he calls the bank of mom and dad, to reach the first rung.
Resources mentioned
Books
Also mentioned

Transcript
00:01 Cold open: the Fed is reading it wrong
Orphe Divounguy · On this episode of the Ryan Vet Show. I feel like the Fed chair is misreading the U.S. economy. 1.2 percentage points of the 1.5% growth is all intellectual property and equipment. AI related, which means that the rest of this economy is barely growing.
Ryan Vet · Our ticket prices dropped almost 40%. Not that people aren't getting their coffee, they're getting smaller coffees, they're not getting the pastry.
Orphe Divounguy · If you wanted to keep your monthly cost at 30% of your income, you needed to come up with a down payment of roughly $790,000. There's a big gap of roughly 4.3, 4.5 million units. So the top end is doing great, right? But the middle and the bottom is really struggling right now. Housing is the heartbeat of the U.S. economy. The Ryan Vet Show.
00:52 Why millennials didn't buy houses, and what changed
Ryan Vet · Welcome to another episode of the Ryan Vet Show. I'm here with Orphe Divounguy, and he is an economist, and he's actually the founder and chief economist of Quantitative Research Group, and he has some really incredible insights on the macroeconomics of the housing market. And I can't wait to talk more about housing because one of the questions I've gotten so much about this show started all the way back in 2009. Why do millennials not buy houses? And at that point in time, they weren't old enough was the answer. But now as millennials are aging and are able to buy houses, we're starting to look at Gen Z buying houses, and we're we're seeing interest rates uh fluctuate, we're seeing consumer spending change, and we're seeing even certain pockets of housing going to be vacant soon as a generation ages out. And we're going to talk about all that on the show today. So, Orphe, thanks for being on the show today. I would love to know a little bit of your professional journey that you've had and just your your career, and then we'll get into understanding what's going on in the economy today.
01:45 Gabon to France to England to Zillow
Orphe Divounguy · Yeah, totally. So, yeah, so I um was born and raised in Africa, in Gabon, a small country on the equator. Um, you know, was born there, raised, raised up in France. Uh, you know, the school system wasn't great uh where I come from. And so I was very blessed, very lucky. My parents were able to afford us, you know, uh a different life. We moved to we moved to France as kids, went through the school French system, uh the French school system. Um, and then later on found my way to the United States. Um I ended up living in England for almost 10 years for my grad graduate degree, right? Did a PhD in economics. Uh, and my focus there was on is macroeconomics, right? Macroeconomics, but specifically the labor market, the housing market, a lot of research on that. Um, then moved up, moved over to the States, did a lot of work on uh um economic policy and the impact of policy on labor and housing markets, and found myself at Zillow. So I worked at Zillow for a while, uh, basically focused on the um impact of uh the big macro, right? We look at, we think of the macro outlook, we look at interest, we think of what's happening with the labor market, with interest rates, uh, the state of the consumer, and how that feeds into uh what we see in the housing market, right? So housing market outcomes. And so that's kind of my background. I started the the uh quantitative research group, the consulting firm that uh supports um home builders, capital allocators, okay, where where do we where do we go next, right? Uh we see all of this uncertainty, uh, and we'd like to figure out, okay, where is demand going to kind of outpace supply? Where should we go in order to kind of kind of capture some of the gains um in that are left in the housing market? Which regions are hot? Which regions are cooling? Uh, where are Americans moving to, right? Moving to and from. So all of that stuff, those are the kind of questions I answer in my research. Uh, but also recently we got the big surge in interest rates that kind of cool down the housing market further. I think we started the year thinking we were going to get a rebound in housing market activity. That rebound didn't materialize. Uh, I work with multifamily operators as well, right? Right now, vacancy rates are elevated, and they're thinking about okay, well, how how do we fill some of those vacancies? Right. And so uh and so I work with them and try to come up with a strategy uh to get those vacant units filled, right? And so so that's kind of my background, and so I'm really, really happy to be on the show with you today.
Ryan Vet · Well, thanks so much, Orphe. I think that's so interesting. And media does a lot uh telling us eggs are so expensive, or your house is you're never going to be able to afford a house, or this generation is not going to ever be able to earn enough because houses are seven times the average income. And some of that's true, and and some of that is fiction. So how do you help someone think about the the housing market in particular, even the economy and the labor market? What where do you go for real sources of information? How do you make sense of it?
05:00 It depends where you live: Kansas City vs. Los Angeles
Orphe Divounguy · Well, I I think it the the first thing is, you know, whenever you hear somebody speak in uh, you know, like the the worst, the this, the that, like those superlatives, I think, you know, ultimately you gotta be you gotta pause there and and and and think about it, right? So it really depends on where you live, right? So you got markets across the country where you can still get into a house uh fairly easily, right? Where basically the typical mortgage payment as a share of income is still roughly, I don't know, 25, 26% of your income. So, you know, if you look at the Midwest uh parts of the Midwest, you go to Kansas City. In fact, by the way, it's why some of those Midwest markets are still growing rapidly, and why rents and prices are rising fast in some of those markets relative to the rest of the country. So even with the higher mortgage rates, right, it's still relatively more affordable to go ahead and either rent or buy house in St. Louis, Missouri, right? Or in even Columbus, Ohio, booming town, Ohio State University, big uh government employer, uh still growing uh uh at a decent pace, right? And then you turn to uh the coast. You know, if you live in New York, or if you live in uh Seattle, or you live in San Jose, California, or even Los Angeles, it's very, very difficult to take, take, you know, to jump from being a renter to becoming a homeowner, right? It's the down payment, right? In in in LA, a couple of years ago, we did the math, right? With the typical home value in LA. Uh if you wanted to keep your monthly cost at 30% of your income, you needed to come up with a down payment of roughly $790,000, right? Just to get right, you know, because the bigger your down payment, the smaller your monthly, your monthly cost, right? Your monthly payment. And so if I wanted to keep my for the typical household, the median income household, if they wanted to keep their monthly payment at 30% of their income, they'd have to come up with a $700 plus thousand dollar down payment, which most people just don't have, right? And so in LA, it's hard. And that's why the share of renters, right? If you look at homeownership rates on the coast, they're very low. Most people rent, right? And so it really depends on where you are in the country. I think there's a lot of opportunity, for example, right now, uh, throughout the Sunbelt. If you look at markets like Austin, Texas, and Dallas and San Antonio, those are markets that have seen a big increase in new construction during the pandemic. We had a record 50-year high increase in new construction during the pandemic that actually depressed rents and prices. You saw press rents and prices actually falling in places like Austin, Dallas, San Antonio, Phoenix, right? And that big decline means that, you know, despite the fact that mortgage rates are what, 6.7% today, right? The decline in prices has made it a little bit more affordable, relatively more affordable. And so some of those markets are markets where there could be an opportunity. Those are markets where, you know, historically Americans have been moving to those places, right? And so buying today in a market like Dallas or Austin, right? Some of those Texas markets, it could potentially be like buying at the bottom. It could be a great opportunity if you're trying to step into the housing market, either as a homeowner, you know, for the first time, or even as an investor, because ultimately there will, you know, you're buying the bottom, right? And so there will be some upside uh going forward.
Ryan Vet · That's really a helpful look at sort of the national landscape. One of the things that we talk about a lot is what's is Gen Z going to ever be able to afford houses and what's that going to look like? And at the same time, we're having the conversation with baby boomers and silent generations leaving their houses behind as they they pass on. So we have this interesting dichotomy where we we have a lot of wealth that has been accumulated in silent generation and baby boomers. And at some point, those houses are going to be vacant. And at the same time, we're we're having conversations about Gen Z not being able to afford houses. Is there ever going to be a meet in the middle, or what's your perspective on that?
09:22 Renting in New York, buying in Alabama, and the bank of mom and dad
Orphe Divounguy · Yeah, look, there are plenty of Gen Z folks that are buying houses. They're renting in New York and they're buying in Alabama, they're buying in Tennessee, right? So, you know, again, it you we see these big headlines, and those big headlines don't often reflect reality on the ground, right? So looking at the data, I encourage people to go look look at the housing data. Uh, you could look at it yourself. There's Zillow, where I was at Zillow, there's Redfin data, and you could kind of compare. You they they produce really nice maps, and you can kind of compare where the opportunities are. So some people are actually saying, hey, I I work in New York, but you know, I really want to be a homeowner. And so maybe I could get in and invest right now in Tennessee, right? I could go to a market that has, you know, where prices are not as high, right? Where it's somewhat affordable, and I'm gonna buy and maybe rent out the unit. And so that's one way people are getting the housing market today. Another way Gen Z are going into the housing market today, you can see it in in uh you know the various surveys out there. One of them that I'm very familiar with is the consumer housing trends report that Zillow publishes. Is basically they're using uh family funds, they're buying, they're co-buying. They're either buying using the what I call the bank of mom and dad, right? Or all right, or they're uh getting friends together, right, and and co-buying, right? That's another way they're getting into housing, you know, they're putting their money together, down payment and everything to get on the first rung of the housing ladder. So that's what Gen Z is doing today. Uh, and of course, you mentioned it, I think ultimately we're going to have this big wealth transfer. You're gonna have a lot of these, you know, older folks that are gonna leave homes to their kids. Uh that's gonna happen. Now, I you know, I am a bit skeptical that you know that big transfer is going to ultimately um, you know, I I think a lot of people say, well, it's gonna change the housing market, it's gonna change the map. Look, you know, a lot the biggest the largest share of older households, older homeowners um that have paid off their homes outright, uh live in uh middle of the country, like the Midwest, right? And the Midwest is still relatively affordable. So even if we get a big supply uh of homes coming on the market in the Midwest, I'm not sure it changes things on the coast where most young people are living close to these big vibrant job markets, right? So, so you know, I hear that a lot. You know, we're gonna have some sort of silver tsunami that's gonna free up the housing market. We're gonna have lots of supply coming. Well, you know, the supply is not likely going to show up on the coasts uh where everybody wants to live. So the coasts are likely going to continue to remain very expensive for the foreseeable future. And then you also have the fact that, you know, with uh, you know, issues related to the climate, uh whether it's the heat or the erosion and the right, the the geography, right? The land, the available land, there's so little land on the coasts to start with that uh that's another constraint to home to building that's going to keep uh housing somewhat expensive uh on the coastal around those coastal markets.
12:49 The pandemic, remote work, and the boom in the in-between towns
Ryan Vet · You keep talking about the coast, and I want to dive a little bit deeper there because I think it's so important. If you look at the pandemic as a milestone in history, obviously it was, but you have a lot of individuals working remote or or having remote jobs, and we've seen this shift between urbanization and people moving to the suburbs. What are you seeing? Are the headlines accurate? Is that just uh good news stories? And where are people actually trying to move if they have remote jobs?
Orphe Divounguy · Yeah, I think people are people, you know, people are going where they can get with where it's relatively more affordable. So they're going where they can get more for less, right? Like more space for less money, right? And so you're seeing a lot of people, you know, I may have a good friend who moved from New York City to Philadelphia, right? I mean, you know, why? Well, Philadelphia happens to be right in the middle between New York and and Washington, D.C. You can get to either places within two hours on a fast train. It's amazing, right? And and Philadelphia is a lot less expensive. Your money will go much further, right? You could get a much nicer space, right, uh, in Philadelphia and still have the opportunity to go into the big city whenever you feel like it. And so we saw that a lot during the pandemic, where people were basically like, oh, I need more space, right? I I can't get stuck in an apartment, right? We saw that during COVID, right? And so a lot of people started moving out a little bit, right? But they stay close to those big job centers, like commuted within commuting distance of these big job centers. You're skating in you, you look around the Boston area, you look around uh, you know, the whole, the whole Connecticut, all of these small towns, like Hartford, right? Connecticut, Providence, Rhode Island. You you look at all these towns that are now booming, they're growing. They're, you know, they're you know, I call them small towns, you know, they're considered metro areas, but they are booming, they're expanding. And the reason they're expanding is people are looking for affordability, right? You look at Buffalo, New York, growing like crazy. You got a lot of college, colleges in the area, right? So you got a lot of highly educated young people trying to find opportunities, and they want to stay, they want to live close to where the jobs are, right? And so those are booming metros near those big, big cities, right? Near the New York, New York metro area where where you know everybody wants to live and work in New York City. So, you know, how can I work in New York City when I can go ahead slightly out, slightly out of town, a little bit further out, uh, and still get into New York City within an hour or two. And I think a lot of people are doing that now. And you see it in the housing data because you know, when you look at price growth and rent growth, you know, it it's actually rents and prices rose faster in the suburbs and exurbs than it did uh inside the big cities.
Ryan Vet · Okay, so uh and is that trend a long-term trend, or are we seeing that more recently?
Orphe Divounguy · So we start, I think we started seeing that more during the pandemic. And and whether or not I think it's gonna stay, yeah, I think it's actually going to stay. And the reason I think it's going to stay is because of, you know, our generation, right, is just not used to 6.7% mortgage rates. And when you add, right, the total price of housing and you combine that with where mortgage rates are today, right, to compute the total monthly cost, and you, you know, you start to add maintenance cost, and you start and you think about taxes and insurance and all of those things, you're right. It's it's a you know, you need you need a pretty large, substantially large income to live in some of these big cities. And so I think that trend is going to continue. When you look at census data though, and you can go very, very far back, and I've done this exercise. What you learn there is that people historically people have always moved, movers at least, the people who choose to move have always gone from a more expensive to relatively less expensive market, right? You look at all the you look at the pairs of uh of uh cities, right, for from and to that people move that people move from and to, right? And it's always from a higher, more expensive city to a relatively more affordable city, right? And so that is so relative affordability is always more attractive. And so, and it's by the way, it's not just housing cost, it's also income, right? It's the labor market opportunities, it's the cost as a share of income, right? As you know, as a measure of affordability that kind of drives a lot of the migration patterns that we've seen that we see in census data for as long as we've had uh the ability to track this stuff.
Ryan Vet · So let's talk more about that migration because that's really interesting. That people are, as I would assume, they have more equity in their house, so they have more wealth they could put towards their next house. They're actually moving to a less expensive market. Is that what you're you're saying?
17:51 Why mobility stalled: hiring, rate lock, and under-market rent
Orphe Divounguy · That's right. That's right. Historically, the majority of moves are always from a relatively more expensive to a relatively slightly more affordable market, right? It's it's you know, it's you, I, you know, I look at this, I've looked at this as long as these variables have been in the the uh data data set, you can you could see it. You could see those patterns. It exacerbated, it got worse during the pandemic when prices and rents soared. You could see it, it it really sped up. Uh right now, though, you made a very good point, is that basically you have a lot of people who are, well, first, mobility has slowed. Why has mobility slowed? Mobility has slowed because first the labor market's not great in terms of higher hiring rates, are the lowest they've been since right after the global financial crisis. So, you know, uh, you know, historically people move because of a job, a new job. And so if the labor market, if you don't see a lot of churn in the labor market, you usually don't see uh strong residential mobility. So you're seeing people staying put. Uh, you have another reason, you have rate lock. We call it rate lock. People who refinanced, uh got themselves really low mortgage rates during the pandemic, and with mortgage rates above 6.7 percent, it doesn't make a lot of sense to move and give up your 3% or 4% mortgage rate. That's another reason people are staying put. And if you look at renters, well, renters are also staying put. You look at retention rates, when you look at tenants and you look at retention sayings, they've been on the rise. One of the reasons tenants are staying put is because you know, rent growth may have slowed, but rents are still higher, right? When we say rent growth, it means that rents are increasing at a slower pace. And the fact that rents, market rents, happen to be higher than your current rent, right, is going to make you want to stay in place. It's gonna want to keep, you know, uh get you to stay put. And so tenants are looking out there and they say, actually, my deal right now looks like a pretty good deal compared to what's out in the market uh today, right? And so so you all of these factors are contributing to a slowdown in residential mobility, and uh and and so that's kind of the big picture. But for those who choose to move, they move to where it's relatively more affordable. For those who choose to move in the housing market today, you'll see that they tend to go to new construction, which is why new home sales have continued to outpace existing home sales in you know, in terms of increase, right? The increase in sales on a year-over-year basis. Well, the reason was that builders were basically giving away uh rate buy downs. They're giving away, all right, they're giving away part of the closing cost. They're really helping with the affordability. So, you know, everything we're seeing in the in the in the economy today is somewhat tied to this affordability squeeze that everyone is facing today.
Ryan Vet · There's a few things that that you brought up that I want to touch on. One is the labor market and how that's evolving. But before we get there, we you know, inflation to some extent is good. Without inflation, the economy can't move forward. But I've never considered is mobility good for an economy? And if we slow down mobility, are there opposite reactions that we need to consider?
Orphe Divounguy · Yeah, so low and stable inflation is good. Ryan Vet Right.
21:21 Getting stuck is the economic problem
Orphe Divounguy · High inflation is the problem, right? Because of course, you know, your your money doesn't go as far. Uh you're you're you're struggling, especially for lower income households. Uh that you know they they they really struggle to keep up, right? Um mobility is actually a good thing. Why is it a good thing? Because it it means people are able to move to better paying jobs, to better opportunities, right? So anything that kind of restricts mobility is going to lead to more inefficient outcomes in the economy. Why? Because people are going to get stuck in places that are not necessarily good for them or even good for. For us as an economy at large, right? So if there's a new technology being invented in uh uh you know in San Francisco, right, and there are needs for new engineers to go build those new technologies, but the engineers cannot get to the work, right? That's a problem, right? That's a problem for those engineers, but it's also a problem for the economy because all of a sudden we can't take advantage of these new technologies. And so residential mobility, churn is a good thing, right? And so the fact that there's low churn in the house in the labor market and the housing market today does not bode well for the US economy going forward.
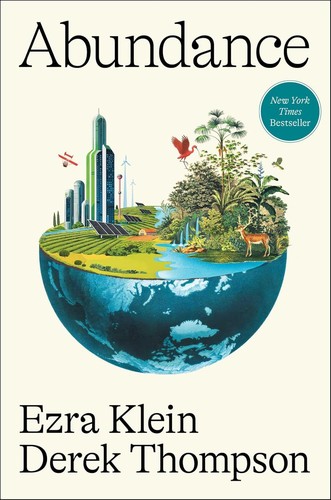
Ryan Vet · That's really helpful to look at. And I I always remember inflation being good, and air quotes for for those of you just listening, not seeing it on video, because in my, you know, when I was getting uh my undergrad business degree, I got that question wrong. I said, no, inflation is bad. And uh my my economics teacher had a whole lesson on that. That was like the you know, the first day of class. So um, you know, healthy, controlled, steady inflation is good, but that's interesting about churn. Now, if you've ever uh heard of the book Ezra by Ezra Klein and Derek Thompson called Abundance, one of the things that they bring up is there's a housing inventory crisis, and that's a lot of the issue that we have today. What would you say to that? Because you just talked about places like San Antonio and Austin booming. You also talked about people moving to new houses if they're they're moving to a more affordable area. So what's happening to inventory? It seems like we might have a lot of old housing inventory, and what happens if that's the case?
23:31 The 4.5 million unit deficit, and housing as the heartbeat
Orphe Divounguy · Yeah, well, so first of all, I you you'll never hear me say that we don't need any more housing. We need more housing. You know, in fact, the more we built, I mean, you look at Austin, Texas, for example, for the longest time, so Austin built like crazy during the pandemic. Amazing. And then as soon as the this big building boom showed up, prices and rent started falling, and everybody started panicking. And they started saying, well, that's it. There's a big bust in Austin, no one's coming here anymore, they must be leaving, right? And if you look at the history, right, you look at the data, people move to where it's relatively more affordable and where they have more abundant options, housing options. And so, you know, you look at Austin today, but migration into Austin hasn't stopped. People are still moving to where it's relatively more affordable and where they're going to have more housing options. And so, for even for a local politician or for a local community, trying to grow their tax base, right? Making things relatively more affordable by maybe by starting with building more housing is always a good thing. Welcoming people, right, by making things relatively more affordable is how you grow your tax base, right? Is how you grow tax revenues without actually hiking tax the tax rate, right? And so so that is so I so I think that's the the key here, right? Is that basically we need to get people moving again. We need to make things relatively more affordable. And the big chunk of, you know, if you look at the inflation numbers, right? 42% or so of core inflation is housing. And so housing happens to be the main it the main thing. It's you know, it's it's what people spend. If you look at your budget, your monthly budget is the bulk of your spending for most households, right? And so it is it is absolutely key that we continue to build more housing throughout the country. When I was at Zillow, I wrote, uh I was the first to come up with this, you know, very simple measure of the housing deficit. You know, where are housing deficits across the country, right? And academics have been debating this forever. And I said, well, let me just make it super simple and not make a bunch of us, you know, come up with a bunch of assumptions about who should be forming a household and who should not, et cetera, et cetera. You if you just count the number of families living in the United States and you compare it to the number of housing units available for rent or for sale in any given year, there's a big gap of roughly 4.3, 4.5 million units. Right? Wow. Very simple. Take the number of families living in the United States, right? Right. So the P there's so many of them that are doubling up. They're sharing a unit with somebody they're not related to. And I guarantee you, a lot of these families would love to have a place of their own, right? So if you take all these people and you compare them to what's available for rent or for sale, right, there's a big gap of roughly 4.5 million units, right? And so, and and of course, it varies across the country, right? So that's the national number, but it varies across the country. You you'll see that in markets that are relatively more expensive. If you look at New York, Seattle, San Jose, San Francisco, Los Angeles, right? Those markets have the biggest housing unit deficits in the country, right? They just don't build enough housing for everybody, right? And so that is a major problem. You look at migration data, people are leaving Los Angeles to go to Texas, right? There's a reason for that. It's become, it's become absurd, right? And so, and so that that's the main, that's the story. You know, housing remains, you know, the key, right? It's it's and I and I say I used to say this a lot, I coined this term, housing is the heartbeat of the U.S. economy. If we make housing affordable, we can get the churn in the labor market, right? We can get people moving to opportunities, and of course, that that's good for economic growth.
Ryan Vet · I love that. That housing is the key, and I agree with that. If you go back to really the 60s and 70s when the American dream term just skyrocketed. The American dream was the perfect little house with the white picket fence and the golden retriever and the 2.2 kids, but a big part of that American dream was homeownership. That was when mortgages became, you know, not 50% down on a five-year mortgage, but it became an accessible 20 or 30-year mortgage. So I do agree that we we see a lot of that. How would you encourage someone to pursue the American dream in an economy where it is a little bit more expensive?
28:18 Is the Fed misreading the US economy?
Orphe Divounguy · Yeah, you know, I'm I'm glad you asked that question because, you know, I was watching the Fed chair last week and I and just thought, I feel like the Fed chair is misreading the US economy. Right? You know, he he talks about strength, right? The economic growth is strong, the labor market is fine, right? And I and we're because the unemployment is 4.1%. And and and I and it and I think the the fact that you're looking at, you know, I think most people see these headlines and they see the average, right? They don't look at the distribution 4.1% unemployment rate. Oh, everything must be fine. No, there are recent graduates that can't find a job that are struggling, highly educated recent graduates that can't find a job, right? Um GDP growth, real GDP grew 1.5% in Q2, it's okay. Trend growth is roughly 2%. Everything must be fine. No, if you go down deeper, what you learn is the one point 1.2 percentage points of the 1.5% growth is all intellectual property and equipment, AI related, it's related to the AI build out, which means that the rest of this economy is barely growing, right? Wow, and so right, and so and so everything is not fine. If you look at consumer sentiment, right, and you see these surveys and people dismiss the surveys and say, oh, the data, the hard data shows the economy is doing great. There's a reason why most people are feeling so uh gloomy about the current state of the economy, right? And and I don't want to take uh shots of the Fed chair on the podcast, but ultimately everything is not fine, and people don't feel fine in the current economy, right? And so, how do we navigate the current economy? You know, I think that's a great question. Um, I wish I had the answer. I think ultimately uh you have interest rates are rising, which are really squeezing, uh keeping people from being able to uh to borrow in order to finance their spending. Prices are rising really rapidly, they're feeling the shock from the oil prices, the the the you know, the the war intensified, which means that basically, you know, we're gonna see prices continue to rise. At the same time, we're seeing the 10-year treasury yield and mortgage rates continue to increase, right? So you're getting hit on the price side of your budget, and you're also getting hit on the um, you know, the price of goods. You're also hit on the price of borrowing, the cost of borrowing, right? Uh real incomes, incomes adjusted for inflation are basically flat. They were falling for a bunch of months, they were falling this year, basically flat. And so, you know, households are really feeling the pinch, right? And so I just thought it was somewhat odd, or you know, this, or or maybe he just was he's just so disconnected from uh from what people are really feeling, right? Uh and so you're not hearing a lot of your polic policymakers really coming to grips, grip with the fact that there is a distribution and that there is a middle and bottom end of that distribution that's really squeezed. Now, at the top end, you know, if you own a home and you have record home equity and you and you can borrow from that home, if you have a lot of stock, uh uh, you know, NVIDIA stock, and the stock market's been okay, right? Right, uh, then you feel okay, right? So the top end is doing great, right? But the middle and the bottom is really struggling right now. And you're not hearing enough economists come out and say, hey, look, there's an affordability squeeze going on right now, right? And that's the reason people are stuck in place, they're not moving, they're not doing anything. Uh, and we really need to pay attention to that part, right? You know, he came out the the Fed chair at Jackson Hole, you know, the the markets took it as a hey, potential rate hike is coming. And I just don't think the Fed should be hiking interest rates in an environment where basically the economy is kind of, you know, on the edge, teetering on the edge, right? And and and there's a big chunk of people that are not doing well. Uh, we I think we need to pay attention to that group because that group is a big group relative to the small group at the very top.
33:03 What a coffee shop's average ticket reveals
Ryan Vet · I think that's so valid. And one of the things that uh I've had for years, I've always had coffee shops and wine bars that I've owned. And it's it's really interesting that I'm not involved in the day-to-day operations. You have an individual of uh service level employees that are making uh uh hourly wage and and they're feeling some of these pressures, and you don't only see it there, but you see the ticket price go down, which I think is a really interesting indicator uh to the to the economy and the state of consumers. We're in a very uh our flagship location is in a very well-to-do area, and our ticket price has dropped almost 40%. Not that people aren't getting their coffee, they're getting smaller coffees, they're not getting the pastry, they're not getting the add-ons. Those are real numbers. Those are real things that are changing, and the ticket count isn't going down. So I think it's you know, it means that people are still buying, but their confidence is declining. And I think that's just a really interesting landscape. So when you look at the labor market, you've talked about highly educated college grads not being able to get a job. A lot of it we can blame on AI, some of that's true, some of that's probably just you know helpful to have a scapegoat. But what are you seeing with some of the entry-level work or maybe some of those service-level jobs? Um, why are we seeing the labor numbers the way they are?
Orphe Divounguy · Yeah, and so so it's really interesting because if you uh, you know, if you look at the the the uh kind of the the you know, if you break it up, break it up into like maybe white collar versus blue collar, right? The the the AI effect is more likely to be on kind of your white-collar uh office uh desk job, especially if it's um uh a job that is easily automated. If it's like the same, if you're doing the same task every day, right, chances are your job is at risk.
Ryan Vet · Like real estate, real estate agency.
34:50 Outbid twice: the agent as therapist
Orphe Divounguy · Potentially, potentially. Although, you know, although I look having bought a house recently, I moved a year ago, one of the things I learned about uh buying a house uh was that it's so you're so emotionally tied to the transaction that by the way, I worked as Zillow, so I was I had all of the data available at my fingertips. And could I have done it just with data? Probably. But you need that human, and you need that human because it's you know, it's a it's a massive decision, it's one of the biggest decisions you will ever make buying a house, right? You you you know, your family, your kids are gonna ra live in that neighborhood, right? You know, you're gonna wake up there every single day, right? And so you're so emotionally tied to the to the thing that very often we um we need that agent, we need that person to I I think of my agent as my therapist, right? I like totally. I mean, like we throughout the home buying process, I was equipped with data, so I knew exactly where to go, what I wanted, and yet because I knew what I wanted and where to go, I ended up picking a house in one of the most difficult housing markets to move into. Like the best. I could never, I could not, I do not regret my decision, the absolute best. I can't you couldn't find a home available in that in that neighborhood, right? And because I because of that, right, I I found what I really needed and what I really wanted, I got outbid twice during that home buying journey. And this is a time where mortgage rates were above 6.5%, right? So, like this is like a year ago, right? I got outbid twice in that neighborhood. So if you really know what you want and you really, you right, it is right and it and it's expensive and it's difficult, and you want the best schools for your kids and all that stuff, you are likely going to need an agent to help you. So I don't really agree that the agent business is going out of style anytime soon, not even with the machines. I mean, Zillow's been around for 20 years, right? And all the data is there. People can just go on their phones and find out anything they want about the house. And yet, when it comes time to putting down real dollars, they call that agent first because that agent is there to comfort you when it's time to cry because you've been outbid a few times.
Ryan Vet · That's good. And I love that you bring back the human aspect of it because for me, a lot of what I do is hey, where where have we replaced the human with technology? I'm all for technology. I'm a living dichotomy, right? I've got an Apple Watch on on and I'm wearing technology, but also say we have too much of it. So I speak out of both sides of my mouth. So I do agree that the human is important.
Orphe Divounguy · Same here, man. Same here.
Ryan Vet · Yeah, I think that distinguishing uh factor is really helpful. Well, we've talked a lot about the economy and everything else. If you could just look forward into the future, what do you see with this next generation? We've got Gen Z uh wrapping up their college career now, they've got a couple years left of high school, and then all Gen Z will be into the adult world, and now Gen Alpha in the next three to four years will be stepping up into that adult world where they're turning 18 the next couple years. What are we gonna see for Gen Alpha? What do you think the the United States labor market housing market's going to look like for them in the next three to five years?
38:27 Gen Alpha, AI, and the $40 trillion caveat
Orphe Divounguy · Yeah, I think ultimately Gen Alpha is going to be much better off than than than than even Gen Z. I think I want to kind of add on a positive note because I actually really believe this. I think there's a transition period, right? Every new technology that came, there's been there was a transition. You know, some jobs were killed, but they were replaced by other jobs, and very often those other jobs were better, better paying jobs. And so Gen Z might feel a little bit of pressure right now to adjust, and they're gonna go through that adjustment, but they're gonna come out much better off than uh than than before, right? And and Gen Alpha is getting to grow up with AI. They're going to make decisions, right? Going to, you know, a university degree, a right, they're going to be making decisions with their lives, right? That are uh basically optimizing for their future outcomes, right? Given the state of the world and the technology that we have available today. And I think that's it's my kids, right? My son is 10 years old, and my, you know, I see them developing and learning, and they do robotics and they code, and they right, and it's amazing to see them uh grow up with so many more tools than we had access to uh growing up. And so AI is not all bad, it's not the boogeyman. I think there's going to be some great opportunities that are gonna come from it. I use it in my work, right? It makes my work so much easier, so much faster, right? You gotta know what you're doing because Claude gets it wrong a lot, okay, still, but but but ultimately, you know, those are tools, right? And those, and if you use those tools the right way, uh they can make you very, very successful. So I I so I I'm looking forward. I'm you know, I'm gonna see there's a transition period, we're going through that transition. Um, you know, millennials and Gen Z, and uh, but I think the next generation is gonna be much better off. Now, I gotta say one thing $40 trillion worth of public debt. That's that's the US government, right? The Fed federal debt. We've crossed the $40 trillion mark. It's gonna have to get paid off, right? To avert a debt. So it's either we're gonna have a debt crisis or taxes are gonna go up, or spending is going to have to get cut, right? And so um the tax bill for the next generation could be very, very large, right? It could be the fiscal situation, it could become a drag on US economic growth, right? Uh, some people may not have a social security to rely on, right? To uh for retirement. And so those are some of the things you you you got these kind of big headwinds uh right in the future. And so that that just kind of tempers my my optimism a little bit, but ultimately, hopeful, at least hopefully, you know, once we're done building the highways for AI, right, the infrastructure, hopefully, right, we get the growth, the kind of growth that we need in order to carry $40 trillion worth of public debt.
Ryan Vet · Well, Orphe, this has just been so interesting, so helpful. And I think you and I share a very similar optimistic perspective looking for Gen Alpha in the future. I know we both have kids in that age range, so I think they have uh an exciting time ahead of them. Uh not free of uh any obstruction, but an exciting time nonetheless. How can people find out about you? You work with companies, you work with uh policymakers, you work with individuals, you you work with a lot of people that that need to hear what you have to offer. How can they find you and get in touch with you?
42:30 Where to find Orphe
Orphe Divounguy · Yeah, so um hello at orphedivounguy.com, my website, orphedivounguy.com, or you can find me on LinkedIn, look me up on LinkedIn. I share all of my uh insights. Uh, you know, I I post regularly. I have a newsletter you can subscribe to. Um and so and I'm very uh, you know, I do podcasts, I'm on TV, always happy to you know to bounce ideas off, you know, with you. So feel free to reach out anytime.
Ryan Vet · Awesome. Well, thank you so much, Orphe, for your time on the show today, and thanks to all the listeners for listening to this episode of the Ryan Vet Show. Until next time, inspire forward.
Orphe Divounguy · Thanks for tuning in to the Ryan Vet Show. Be sure to subscribe, comment, and like this episode. Plus, share it with someone who needs to hear it.
Full show notes
Subjects in this episode
COLLIDE · A weekly essay by Ryan Vet

Read the thinking behind every episode.

Join 23,000+ leaders reading Every Tuesday at 4pm ET.

Free. Weekly. Unsubscribe anytime.
Ryan Vet