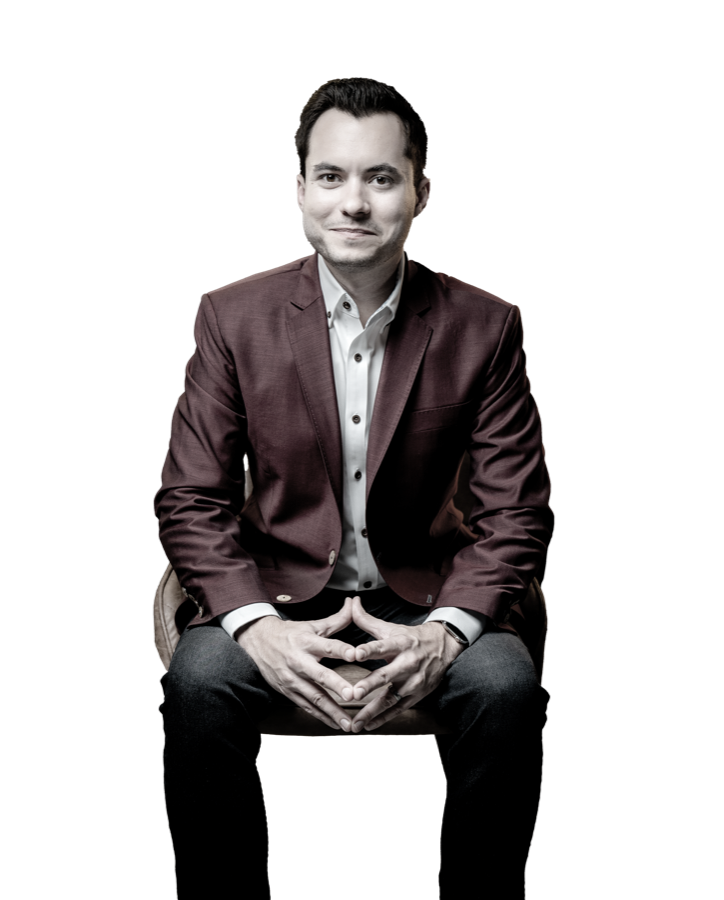
Orphe Divounguy
Founder and chief economist, Quantitative Research Group
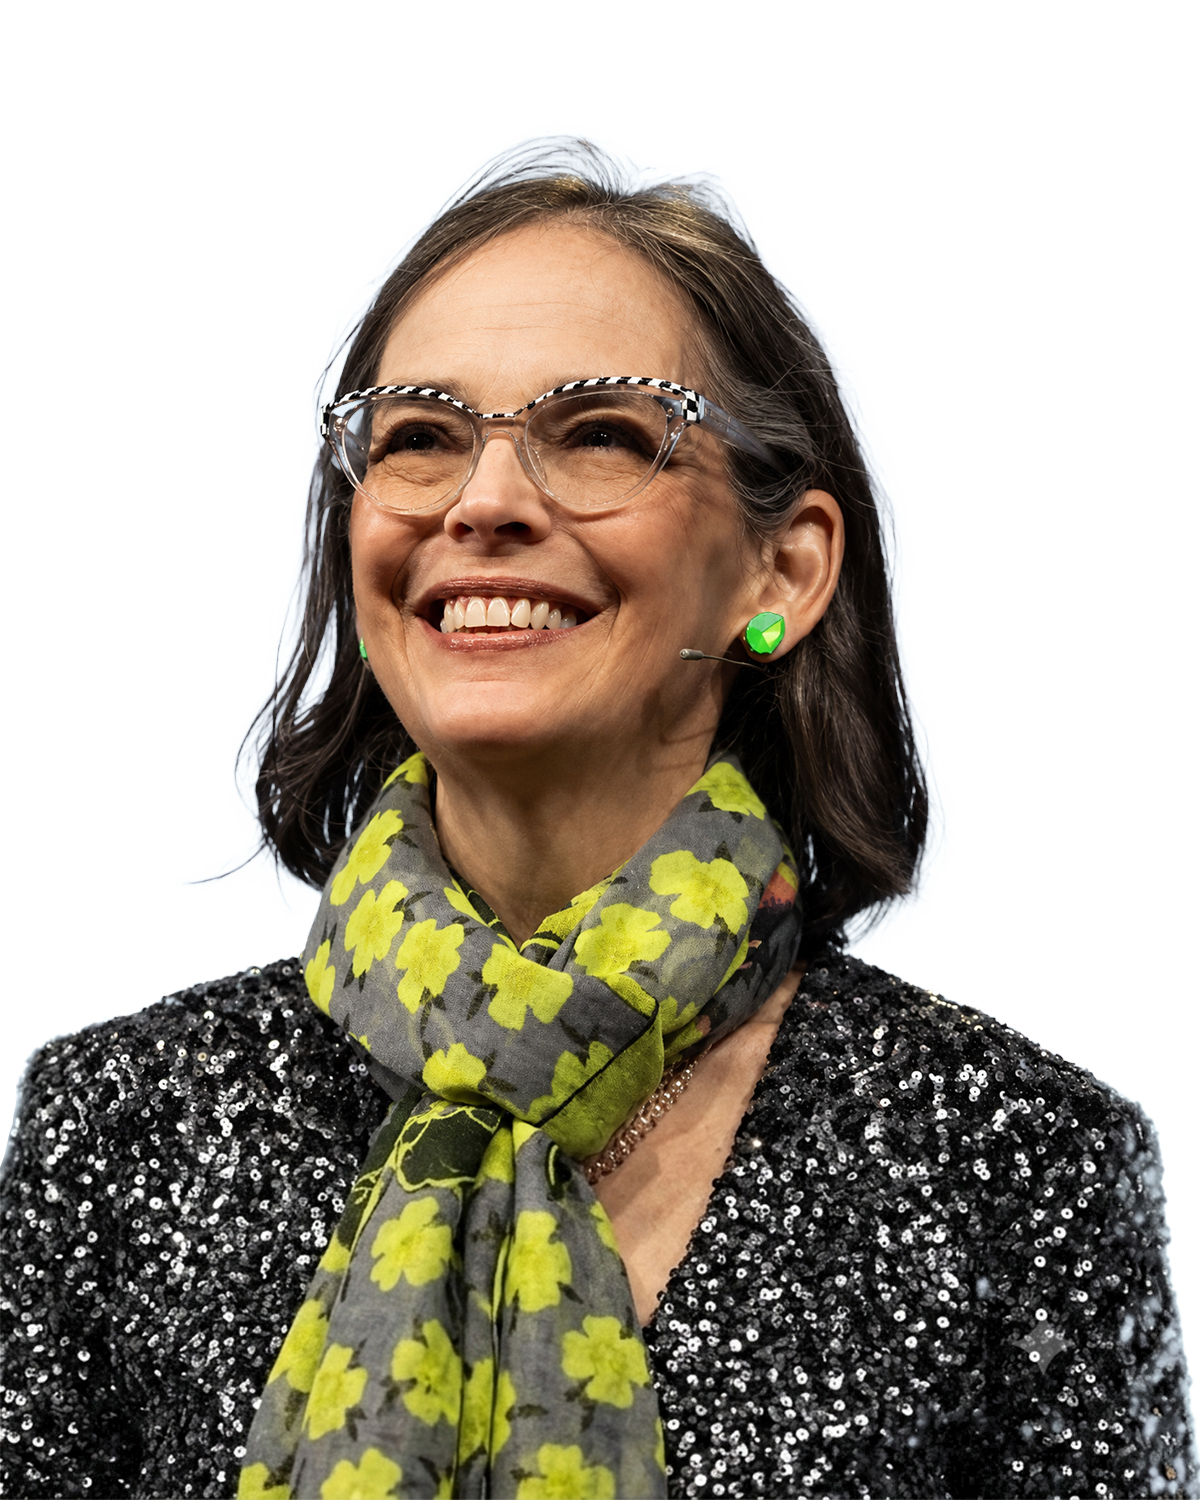
Orphe Divounguy is the founder and chief economist of the Quantitative Research Group and a former Zillow economist, where he built the first simple measure of the national housing deficit. He holds a PhD in Economics, is a LinkedIn Top Voice, and hosts the podcast Everyday Economics. His argument is that housing is the transmission mechanism for the rest of the American economy, and that the official read of that economy is misleading.
Reviewed September 2026Orphe Divounguy has spent nearly two decades helping executives, investors, policymakers, and the public make sense of the economy, translating complex analysis of housing, labor markets, and fiscal policy into clear, forward-looking guidance they can act on. He is the founder and chief economist of the Quantitative Research Group, and a former Zillow economist. His research and economic commentary reaches millions through national media and through his own podcast, Everyday Economics. He holds a PhD in Economics.
He was born and raised in Gabon, a small country on the equator. His parents moved the family to France when he was a child, for the schools, and he went through the French school system. He spent almost 10 years in England earning a PhD in economics, focused on macroeconomics and specifically on the labor and housing markets. He then moved to the United States, worked on economic policy and its effects on those same markets, and joined Zillow, where he studied how the macro picture, interest rates, the labor market, the state of the consumer, feeds through into housing outcomes.
At the Quantitative Research Group he consults for home builders, capital allocators, and multifamily operators on where demand will outrun supply, which regions are heating and cooling, and where Americans are actually moving to and from. The work that travels furthest is a deliberately simple one he built at Zillow: count the families living in the United States, compare that against the housing units available to rent or buy, and take the gap. No assumptions about who ought to be forming a household. The answer comes out around 4.3 to 4.5 million units short, concentrated in the coastal metros where people most want to live.
On The Ryan Vet Show, Orphe Divounguy makes an argument more pointed than economists usually make out loud: the official read of the American economy is misleading, and housing is the reason. Of the 1.5% real GDP growth in the second quarter, he notes that 1.2 percentage points came from intellectual property and equipment tied to the AI build-out. Strip that out and the rest of the economy is barely moving. Unemployment at 4.1% looks healthy until you go looking for recent graduates who cannot find work. His line for it is that most people see the headlines and see the average, and never look at the distribution.
The number that lands hardest is a down payment. For a median-income Los Angeles household to keep monthly housing costs at 30% of income against the typical local home value, he calculates the down payment would need to be roughly $790,000. That is why homeownership rates on the coasts are so low, and why the answer to where Gen Z is buying turns out to be somewhere else entirely. They are renting in New York and buying in Alabama and Tennessee, co-buying with friends, or reaching the first rung through what he calls the bank of mom and dad.
His central claim is that American mobility has stalled for three reasons at once, and that the stall is not a side effect but the problem itself. Hiring rates are the weakest since just after the global financial crisis. Homeowners will not give up pandemic-era 3% and 4% mortgages with market rates near 6.7%, which he calls rate lock. And renters are staying because market rents now exceed what they already pay. If engineers cannot move to where a new technology is being built, the technology does not get built. Host Ryan Vet brings a countertop version of the same country: at his flagship coffee shop the average ticket is down almost 40% while the ticket count holds steady. Smaller coffees, no pastry.
Housing is the heartbeat of the U.S. economy.
I feel like the Fed chair is misreading the US economy.
1.2 percentage points of the 1.5% growth is all intellectual property and equipment.
Who is Orphe Divounguy?
He is the founder and chief economist of the Quantitative Research Group, an economic consulting firm advising home builders, capital allocators, and multifamily operators on where housing demand will outrun supply. He is a former Zillow economist, holds a PhD in Economics, is a LinkedIn Top Voice, and hosts the podcast Everyday Economics.
What is the housing deficit, and how big is it?
It is the gap between the number of families living in the United States and the number of housing units available to rent or buy. Divounguy built the measure at Zillow and kept it deliberately simple, with no assumptions layered in about who should be forming a household. The gap comes out at roughly 4.3 to 4.5 million units, with the largest shortfalls in New York, Seattle, San Jose, San Francisco, and Los Angeles.
What does Orphe Divounguy mean by housing is the heartbeat?
It is his own phrase for housing as the transmission mechanism of the wider economy. Make housing affordable and you restore churn in the labor market, which restores growth. He notes that roughly 42% of core inflation is housing, so the same lever moves prices, mobility, and opportunity at once.
What is rate lock?
It is his term for homeowners who refinanced into 3% and 4% mortgages during the pandemic and will not move while market rates sit near 6.7%. Giving up the old rate means a far larger monthly payment for the same house, so people stay put. It is one of three forces he identifies behind the collapse in American mobility.
Will the silver tsunami make housing affordable again?
He is skeptical. The wealth transfer is real and homes will pass to the next generation, but the largest share of older homeowners who own outright live in the Midwest, which is already relatively affordable. The supply does not appear on the coasts where young people cluster around big job markets, so he expects those markets to stay expensive.
Read the thinking behind every episode.
Join 23,000+ leaders reading Every Tuesday at 4pm ET.
Check your inbox to confirm. The next COLLIDE lands Every Tuesday at 4pm ET.